Financial Modelling for Beginners: A Practical 2026 Guide (with DCF Walkthrough)
By Muskan Nagpal, Admission Counselling Manager at Meritshot · Published 21 September 2026
Financial modelling is the single most useful skill in investment banking, equity research, private equity and corporate finance — and the one most beginners find intimidating because guides jump straight to jargon. This one doesn't. It explains what a financial model actually is, the handful of model types you need to know, and then walks through a discounted cash flow (DCF) model step by step so you can see how the pieces fit. By the end you'll understand not just what a model is but how one is built.
It's written for beginners and career-switchers — no finance degree assumed. If you're mapping out the wider path into the field, see how to become an investment banker in India; if you want to know where modelling sits among the other skills, see the skills you learn in an investment banking course.
The short answer: what is financial modelling?
Financial modelling is the practice of building a structured spreadsheet that represents a company's financial performance and uses assumptions to forecast its future. At its core, a model links a company's income statement, balance sheet and cash flow statement so that changing one assumption — say, revenue growth — flows correctly through all three and updates the outputs. Bankers and analysts use models to forecast performance, value companies, and analyse deals such as mergers, acquisitions and buyouts.
Put simply: a financial model is a company's finances turned into a flexible calculator, so you can ask "what if?" and get a rigorous answer.
Why financial modelling matters so much
Modelling is the workhorse skill of high finance for one reason: almost every important decision runs through a model. Pricing an acquisition, deciding whether a company is worth investing in, advising on an IPO, testing whether a buyout's returns work — all of it depends on a model. That's why analysts spend a large share of their time in Excel, and why deal-ready modelling ability commands a premium in hiring. It's a skill you can demonstrate — a portfolio of models you can defend in an interview signals capability far more convincingly than a certificate alone.
The core model types you need to know
You don't need dozens of model types to start. Five cover the vast majority of the work.
1. The three-statement model. The foundation. It links the income statement, balance sheet and cash flow statement into one integrated, dynamic model. Master this first — every other model is built on top of it.
2. The DCF (discounted cash flow) model. Values a company based on its projected future cash flows, discounted to today's value. The most important valuation model, and the one we walk through below.
3. The comparable company analysis ("comps"). Values a company by comparing it to similar listed peers using multiples such as EV/EBITDA or P/E. Faster than a DCF and market-based rather than assumption-based.
4. The LBO (leveraged buyout) model. Models how a private-equity firm acquires a company using significant debt and calculates the returns. Central to private equity.
5. The M&A / merger model. Tests whether an acquisition increases or decreases the acquirer's earnings per share (accretion/dilution).
If you learn the three-statement model and the DCF well, you'll have the foundation for all the others.
A step-by-step DCF walkthrough
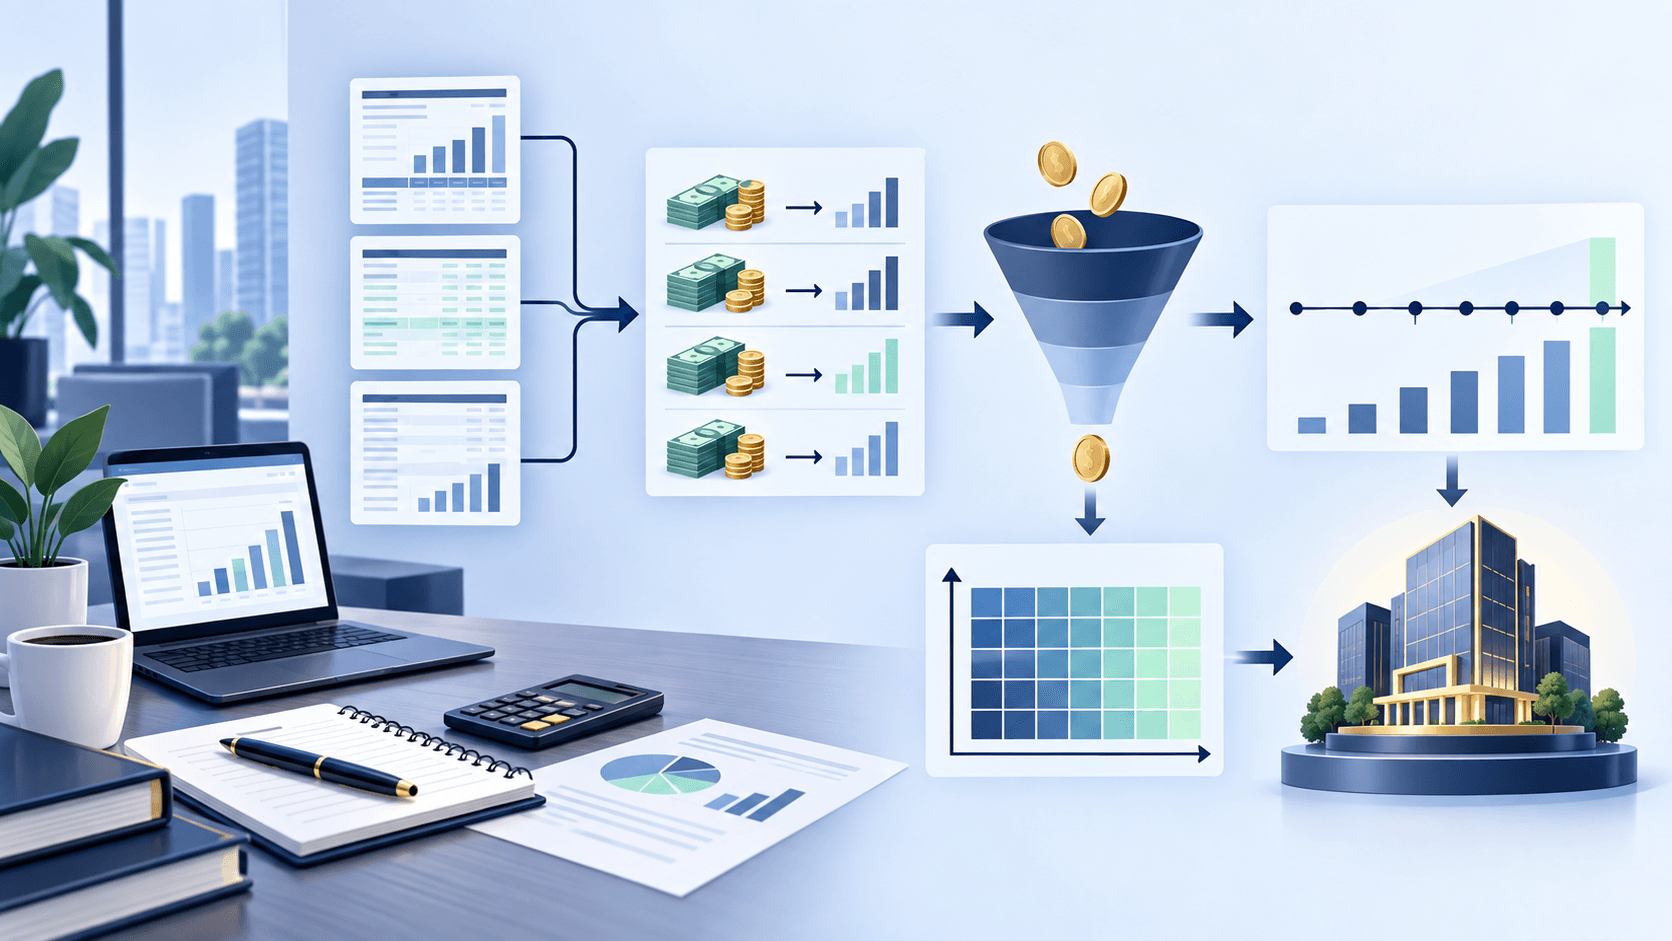
The DCF intimidates beginners, but the logic is simple: a company is worth the cash it will generate in the future, adjusted for the fact that money later is worth less than money now. Here's how a DCF is built, step by step.
Step 1 — Forecast free cash flows
Project the company's free cash flow (the cash it generates after operating expenses and reinvestment) for a forecast period, usually five to ten years. This comes from your three-statement model's revenue, margin and reinvestment assumptions.
Step 2 — Choose a discount rate (WACC)
Money in the future is worth less than money today, so future cash flows are "discounted." The discount rate used is the weighted average cost of capital (WACC) — essentially the blended rate of return the company's investors expect, reflecting both debt and equity. A higher WACC means future cash is discounted more heavily.
Step 3 — Discount the cash flows to present value
Each year's forecast cash flow is divided by a discount factor based on the WACC, converting it into today's money (its "present value"). Cash flows further in the future are worth proportionally less.
Step 4 — Calculate the terminal value
A company doesn't stop generating cash after your forecast period. The terminal value captures all the cash flows beyond it, usually via a perpetual growth assumption or an exit multiple, then discounts that back to present value too. The terminal value is often the largest single component of a DCF — which is why its assumptions deserve scrutiny.
Step 5 — Sum to enterprise value, then derive equity value
Add the present values of the forecast cash flows and the terminal value to get the enterprise value. Adjust for net debt (subtract debt, add cash) to arrive at the equity value — what the company's shares are collectively worth.
Step 6 — Sanity-check and sensitise
No DCF is "correct" — it's only as good as its assumptions. Run sensitivity analysis: vary the WACC and growth rate to see how much the valuation swings. If a small change in one assumption moves the value enormously, that tells you where the model's real uncertainty lives.
The skill isn't just building the DCF — it's understanding which assumptions drive the output and being able to defend them. That judgement is what separates someone who ran a model from someone who understands one.
How to actually learn financial modelling
Reading about modelling is not the same as being able to do it. A few principles that genuinely work:
- Build, don't just watch. You learn modelling by constructing models yourself, making mistakes, and fixing them — not by watching tutorials. This is the single most important point.
- Start with one company end-to-end. Build a full three-statement model for one listed company, then a DCF on top of it. Then repeat for a company in a different sector.
- Get feedback. The fastest accelerator is having someone experienced critique your model — spotting the broken link, the unrealistic assumption, the formatting that makes it unauditable. This is the part that's hard to replicate alone, and the main reason structured programs with mentorship produce stronger modellers.
- Master Excel fundamentals. Clean, well-structured, auditable models matter as much as correct ones. A senior banker needs to check your work quickly.
- Build a portfolio. Keep the models you build. Two or three defensible models are worth more in an interview than any certificate.
If you want a structured path with feedback on the models you build, Meritshot's PG Program in Investment Banking covers three-statement, DCF, LBO and M&A modelling with 1:1 mentorship and real deal case studies — the applied practice that turns modelling from intimidating to second nature.
Common beginner mistakes
- Jumping to LBO/M&A models first. Without a solid three-statement foundation, advanced models produce confident-looking nonsense. Sequence matters.
- Hard-coding numbers instead of linking them. A model's power is that assumptions flow through automatically. Typing fixed numbers breaks that and hides errors.
- Over-trusting a single output. Always sensitise. A model gives a range and a logic, not a single "true" answer.
- Neglecting formatting and structure. An unauditable model is a liability, however clever. Clean layout is a real skill.
- Memorising instead of understanding. Being able to explain why a DCF works beats reciting the steps — interviewers probe for reasoning.
Frequently asked questions
What is financial modelling in simple terms? Financial modelling is building a structured spreadsheet that represents a company's finances and forecasts its future using assumptions. It links the income statement, balance sheet and cash flow so that changing one input updates everything, letting analysts forecast performance, value companies and analyse deals.
Is financial modelling hard to learn for beginners? It's very learnable, but it's a build-it skill, not a read-about-it skill. Beginners who construct models themselves — starting with a three-statement model, then a DCF — progress far faster than those who only watch tutorials. Structured feedback on your own models accelerates it significantly.
Do I need to be good at maths to learn financial modelling? No advanced maths is required — the arithmetic is mostly addition, multiplication and division handled by Excel. What matters more is logical thinking, attention to detail, and understanding how the financial statements connect. Comfort with numbers helps, but you don't need to be a mathematician.
How long does it take to learn financial modelling? With focused practice, you can build a competent three-statement model and DCF within a few weeks to a couple of months. Genuine fluency — building cleanly and fast under real conditions — comes with repetition over several months. Structured programs compress this by providing feedback and real case studies.
What is a DCF model? A discounted cash flow (DCF) model values a company based on its projected future free cash flows, discounted to present value using the weighted average cost of capital (WACC). It sums the present value of forecast cash flows and a terminal value to estimate enterprise value, then adjusts for net debt to reach equity value. It's the most important valuation model in finance.
Which financial model should I learn first? Start with the three-statement model — it links the income statement, balance sheet and cash flow, and every other model (DCF, LBO, M&A) is built on top of it. Once that's solid, learn the DCF for valuation. Attempting advanced models before mastering the three-statement foundation is the most common beginner mistake.
This guide explains standard financial modelling concepts as practised in investment banking and corporate finance. It is educational and not investment advice.